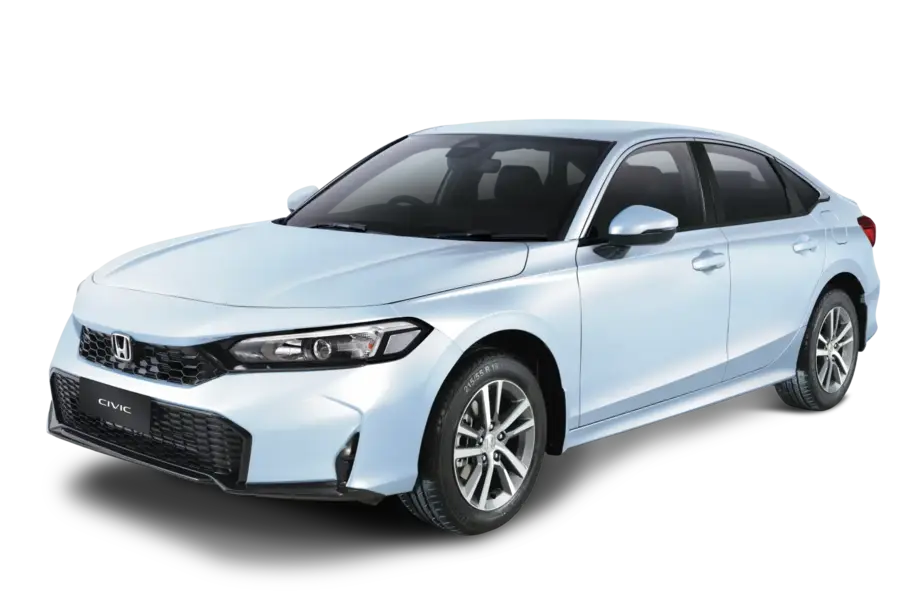
Establish the bank-approved financing amount before comparing monthly payments. With a Rs 3m loan against Honda’s Rs 10.1m listed RS price, the vehicle-price contribution alone is Rs 7.1m, before additional charges. The instalments below are mathematical scenarios, not bank offers.
Start with the financing ceiling
Honda’s Pakistan page lists Civic RS at Rs 10,100,000, checked on 24 September 2026. [1] SBP’s September 2021 circular specifies a Rs 3m aggregate auto-finance limit, and its May 2022 circular limits tenure to three years for vehicles above 1,000cc. BankIslami’s published product material also references the Rs 3m limit and the engine-based tenure distinction. Confirm the current rules and your eligibility with the bank; specialised schemes can have different conditions. [2,3,4]
At that illustrative Rs 3m financed amount, Rs 10.1m minus Rs 3m leaves Rs 7.1m payable towards the car price. Registration, insurance or takaful, processing, tracking and other charges are additional unless the written offer explicitly includes them. Existing borrowing can reduce eligibility; a regulatory maximum is not an approval.
Three-year repayment sensitivity
These examples finance Rs 3,000,000 over 36 end-of-month payments with no balloon, using a nominal annual rate divided by 12 and monthly reducing-balance amortisation. The 15%, 18% and 21% rates are deliberately hypothetical—not current bank quotes. Totals use unrounded monthly values, then round to rupees.
| Assumed annual rate | Monthly payment | 36-payment total | Markup component |
|---|---|---|---|
| 15% | Rs 103,996 | Rs 3,743,855 | Rs 743,855 |
| 18% | Rs 108,457 | Rs 3,904,459 | Rs 904,459 |
| 21% | Rs 113,025 | Rs 4,068,907 | Rs 1,068,907 |
A lower instalment can conceal a larger final payment
Ask whether the quote has a residual or balloon amount. If it does, compare the deposit plus all scheduled payments plus the balloon and fees—not the monthly figure alone. A plan with an unpaid final balance is not comparable to the fully amortising table above.
Request the Key Fact Statement, rate basis, reset dates, total payable amount, early-settlement rules and overdue-payment charges. For Islamic financing, ask for the actual rental and ownership-transfer schedule instead of treating this conventional amortisation example as the bank’s contract.
Test affordability after normal household spending
Add fuel, insurance renewals, servicing and parking to the monthly repayment. Then ask whether the amount remains manageable after a temporary income reduction or an unexpected bill. Do not use expected resale proceeds to cover payments due before you sell.
Obtain written quotes on the same day with the same deposit, financed amount and tenure. That makes the comparison useful. If the upfront contribution is too large, compare a lower-priced variant or delay the purchase; stretching an unsupported calculator term does not make a bank finance it.
Continue your research
Verify before paying
- Current eligibility and total existing auto borrowing
- Key Fact Statement and full repayment schedule
- Balloon or residual amount, if any
- Insurance, tracker, processing and settlement charges
Sources and corrections
The current variant and price record links to the official manufacturer or authorised distributor. CarRates writes original analysis and does not reproduce another publisher’s article.